Introduction
Zempler Bank offers a genuine UK business bank account from £0 per month, with app and online banking, Post Office cash deposits and built-in tools for invoicing, receipts and cashflow. In this Zempler Bank review, we look beyond the headline price to decide whether Business Go represents good value for a startup or small business.
This independent Zempler review also draws on our own application and account experience. We applied for a Zempler account and used it ourselves. Our application questions were straightforward, the process felt smooth and seamless, and the account was opened within 24 hours after a few manual checks. That was our individual experience, not a promise of how quickly every application will be approved.
The short version is that Zempler has a compelling entry-level proposition for a founder with light payment activity. Business Go removes the monthly account fee without stripping out the everyday tools many young businesses need. However, only three outgoing payments or transfers are included each month, and cash, ATM and foreign-currency usage can create extra costs. The right question is not simply whether Zempler is free. It is whether Zempler’s charging model fits the way your business moves money.
Commercial disclosure: Startup Deals has an approved tracked application route to Zempler Bank and may earn a commission if you apply through it. There is currently no exclusive Startup Deals cashback offer, joining bonus or customer promo code. This review is independently written and the commercial relationship does not determine our verdict.
Contents
- Startup Deals verdict
- Zempler at a glance
- Zempler pricing: what will it actually cost your startup?
- Is Zempler Business Go really free?
- Our experience opening a Zempler account
- What is Zempler like to use?
- Zempler’s business tools
- Paying cash into Zempler
- Is Zempler Bank safe and FSCS protected?
- Who can open a Zempler account?
- Is Zempler Bank good for startups?
- When Zempler might not be the best choice
- Zempler Bank pros and cons
- Alternatives to Zempler Bank
- How to apply for a Zempler account
- Frequently asked questions
- Final verdict
Startup Deals verdict
Our Zempler Bank review finds that Business Go is worth considering for a new UK business that wants a regulated bank, FSCS protection for eligible deposits and practical money-management tools without committing to a monthly fee. As a Zempler review written for founders, our assessment places particular weight on the total cost of everyday use.
Its best fit is a sole trader, freelancer, consultant or small limited company that receives payments electronically, makes relatively few outbound transfers and mainly spends in sterling. For that profile, the combination of free incoming payments, three included outgoing payments and built-in admin tools can be genuinely economical.
The proposition weakens as transaction volume rises. Business Go charges 35p for each outgoing payment or transfer after the three monthly inclusions. It also charges at least £4 for each Post Office cash deposit, £2 for a UK cash withdrawal and 2.99% for non-sterling card transactions. A business choosing solely on the £0 monthly price could therefore make the wrong decision.
Business Extra is the more credible middle tier for firms that send more payments, withdraw cash or spend abroad. Business Pro offers a much larger payment allowance and account-management features, but at £19 per month it needs a clear operational justification. Zempler can be good value, but value depends on behaviour rather than the badge attached to the plan.
Zempler at a glance
| Decision point | Startup Deals assessment |
|---|---|
| Best for | UK startups and small businesses wanting straightforward digital banking with no monthly Business Go fee |
| Biggest strength | A regulated UK bank account with FSCS protection and useful business-admin tools on the free tier |
| Main watch-out | Only three outgoing payments or transfers are included on Business Go, with usage charges elsewhere |
| Our experience | Smooth application, straightforward questions, a few manual checks and our account opened within 24 hours |
| Monthly plans | Business Go £0, Business Extra £9, Business Pro £19 |
| Cash deposits | Available at UK Post Offices for a £4 minimum fee or 0.55% of the amount deposited |
| Our overall view | Strong for light, UK-focused use; less convincing for payment-heavy, cash-heavy or international businesses |
Zempler Bank review of pricing: what will it actually cost your startup?
The pricing analysis in this Zempler Bank review starts with three current business account tiers. All three include free and unlimited incoming payments and transfers. The important differences are the number of included outgoing payments, ATM and overseas card charges, cashback and the level of account support.
| Feature or fee | Business Go | Business Extra | Business Pro |
|---|---|---|---|
| Monthly account fee | £0 | £9 | £19 |
| Incoming payments and transfers | Free and unlimited | Free and unlimited | Free and unlimited |
| Outgoing payments and transfers | 3 free per month | 20 free per month | 500 free per month |
| Additional outgoing payments | 35p each | 35p each | 35p each |
| UK cash withdrawal | £2 | Free | Free |
| Overseas cash withdrawal | £3 | Free | Free |
| Non-sterling card transaction | 2.99% | Zempler fee-free | Zempler fee-free |
| Post Office cash deposit | £4 minimum or 0.55% | £4 minimum or 0.55% | £4 minimum or 0.55% |
| Cashback on eligible card spend | None | Up to 0.5% | Up to 1% |
| In-app messaging | No | Yes | Yes |
| Dedicated telephone account management | No | No | Yes |
| Interest-earning savings pot | No | No | 0.75%, with limits |
Prices and features checked against Zempler’s published pricing on 13 September 2026. Terms, eligibility, exclusions and limits apply. Zempler says international transfer fees are shown in the app or Online Banking, so businesses sending money abroad should obtain a live quote rather than assuming a fixed cost.
Which plan offers the best value?
Business Go is strongest for light users. If you make three or fewer outgoing payments per month, rarely handle cash, avoid ATM withdrawals and spend in sterling, your core account charges could remain at £0. This can suit a pre-revenue company, a consultant with a small number of suppliers or a freelancer who mainly receives client payments and pays expenses by card.
Business Extra is a usage decision, not simply an upgrade. Its £9 monthly fee buys 17 more included outgoing payments than Business Go, free cash withdrawals, fee-free card spending abroad as charged by Zempler, in-app messaging and the potential to earn tiered cashback on eligible card purchases. Payment allowances alone do not make Extra cheaper until activity is much higher: 17 additional payments at 35p would cost £5.95 on Go. Extra starts to make more sense when you value several benefits together or make materially more than 20 payments.
Business Pro is aimed at busier operations. It includes 500 outgoing payments, five free additional cards, dedicated telephone account management, an interest-earning savings pot and up to 1% tiered cashback on eligible spend. A growing firm with payroll, many suppliers or delegated spending may see value, but a small founder-led business should not pay £228 a year without using the extra capacity.
Worked monthly cost examples
These Zempler Bank review examples use published fees and are illustrations, not personalised quotations.
| Example usage | Business Go estimated charge | What it suggests |
|---|---|---|
| 3 outgoing payments, no cash or foreign spend | £0 | The headline free account can genuinely remain free |
| 15 outgoing payments, no other charged activity | £4.20 | Still below Extra’s £9 monthly fee on transfers alone |
| 30 outgoing payments, no other charged activity | £9.45 | Slightly above Extra’s monthly fee before valuing Extra’s other benefits |
| One £500 Post Office cash deposit | £4 minimum | The percentage is £2.75, so the minimum applies |
| One £1,000 Post Office cash deposit | £5.50 | Cash handling costs rise with the deposit amount |
| £1,000 of non-sterling card spending on Go | £29.90 | Frequent overseas spending can quickly outweigh the £0 monthly fee |
At 29 outgoing payments in a month, Business Go would charge £9.10 for the 26 payments beyond its free allowance. That is just above Business Extra’s £9 fee, before considering Extra’s 20-payment allowance, cash withdrawals, foreign card spending and cashback. The break-even point is therefore driven by the entire usage pattern, not transfers alone.
Is Zempler Business Go really free? Our Zempler Bank review
Business Go has no monthly or annual account fee. That distinction is central to this Zempler Bank review because it does not mean every way of using the account costs nothing.
The account includes free and unlimited incoming payments and transfers, a free initial card and three outgoing payments or transfers per month. After that, outgoing payments cost 35p each. Zempler’s published pricing also lists a £2 UK cash-withdrawal fee, £3 overseas cash-withdrawal fee and a 2.99% non-sterling card-transaction fee for Business Go.
Cash deposits at a UK Post Office cost a minimum of £4 or 0.55% of the amount deposited, whichever produces the applicable charge. Zempler publishes a standard cash-deposit limit of £6,000 per day across its current business plans, while noting that limits apply and higher limits may be available.
Our Zempler Bank review therefore treats Business Go as a no-subscription account, not universally free banking. It can be excellent value when its inclusions match your habits. It can be poor value if your business is selected for its £0 label while regularly triggering transaction charges.
Our Zempler Bank review experience: opening an account
For this Zempler Bank review, we completed the application ourselves rather than assessing the account exclusively from marketing pages.
The onboarding process was smooth and seamless. The questions were straightforward and the flow was easy to follow. After submission, Zempler carried out a few manual checks. Our account was opened within 24 hours, after which we accessed and used it.
This experience gives us useful evidence about the application journey and initial account interface. It does not allow us to claim that every applicant will be approved, that all accounts open within 24 hours or that manual checks will be the same for every business. Zempler says it verifies personal and business details, applies KYC, fraud and application checks, and may request further information.
Application complexity is likely to depend on the business structure, ownership and sector. Limited-company details can be pulled from Companies House, while partnerships, charities, LLPs and public-sector organisations may need to provide more information. Businesses with overseas persons with significant control or more complex ownership should expect additional checks.
What is Zempler like to use? Our Zempler Bank review findings
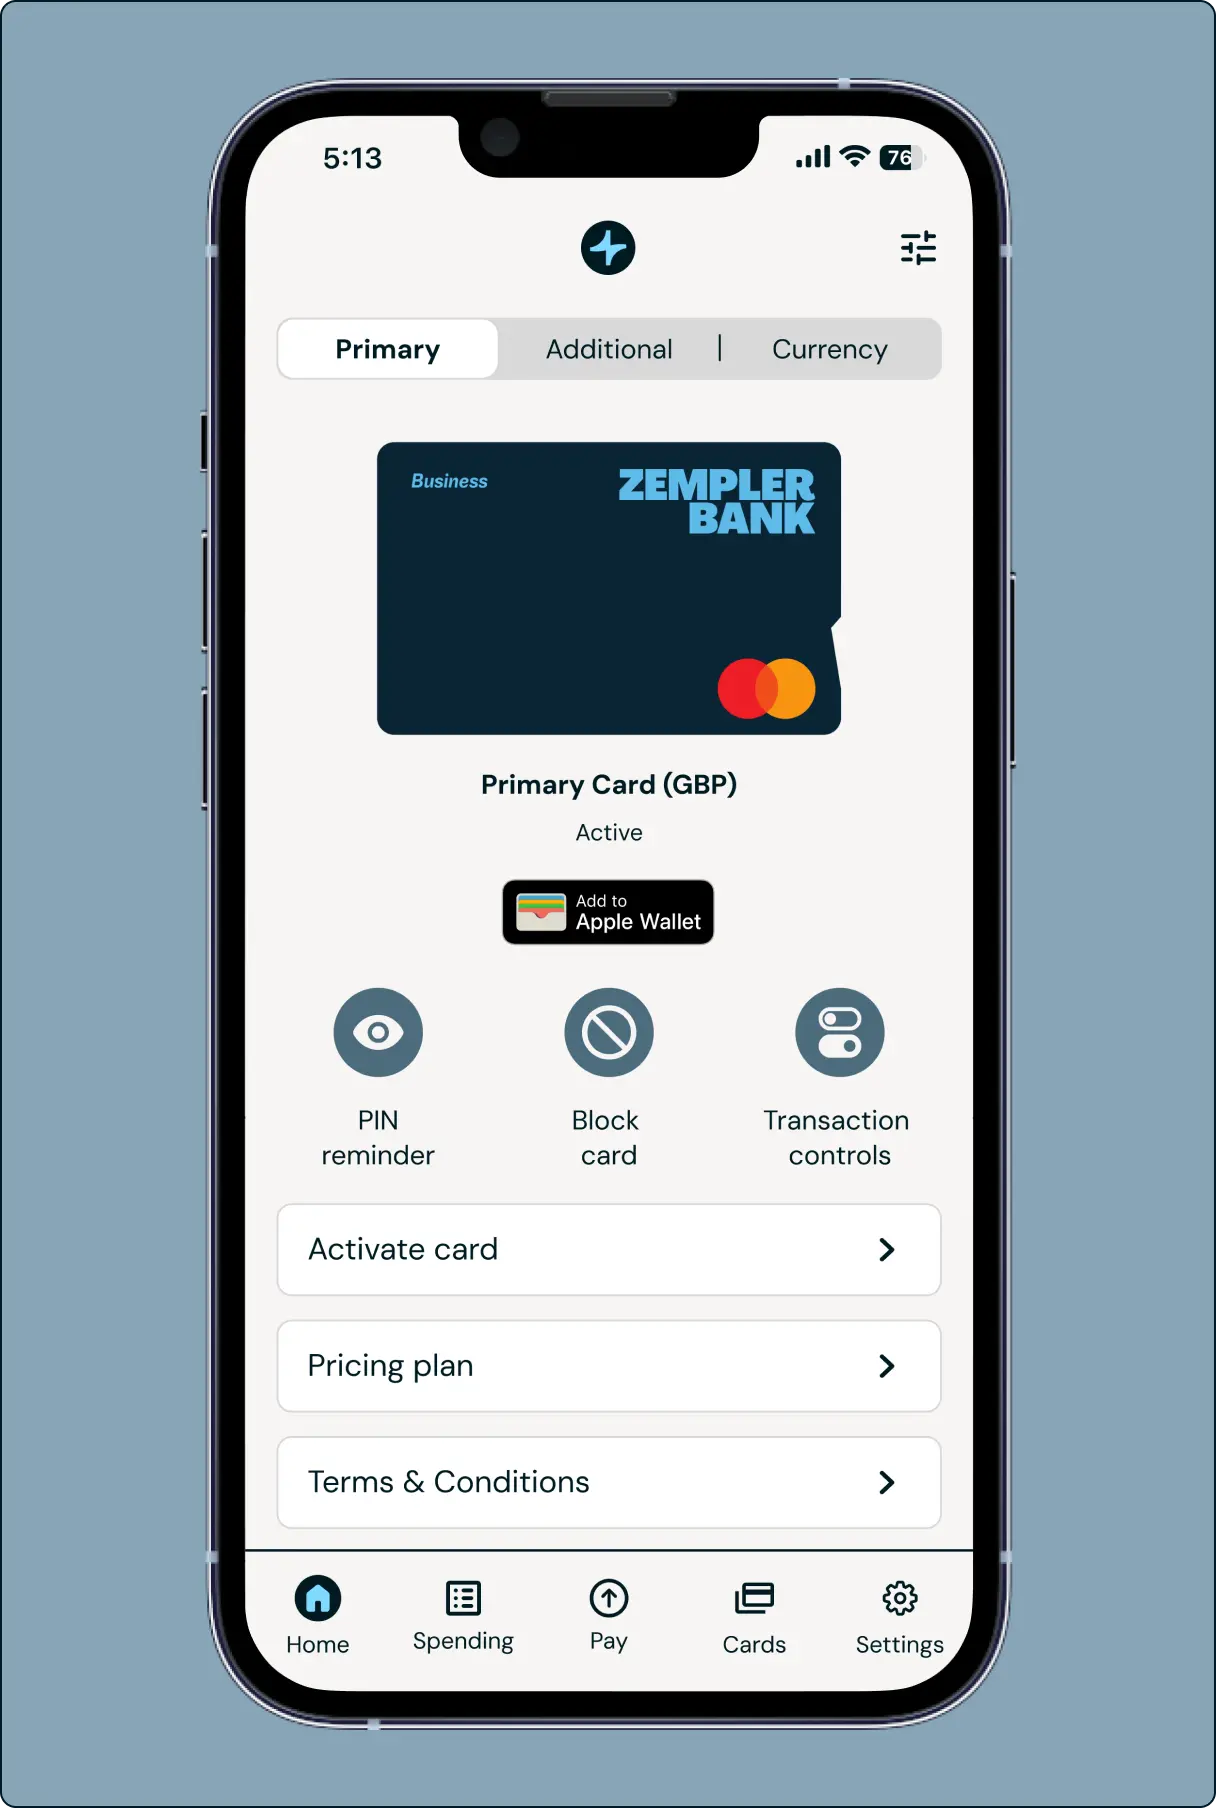
Our first-hand Zempler Bank review impression after gaining access was positive. We found the user interface slick, smart and easy to navigate. Core banking features were logically organised, and the account felt as though it contained the essentials required to run a small business.
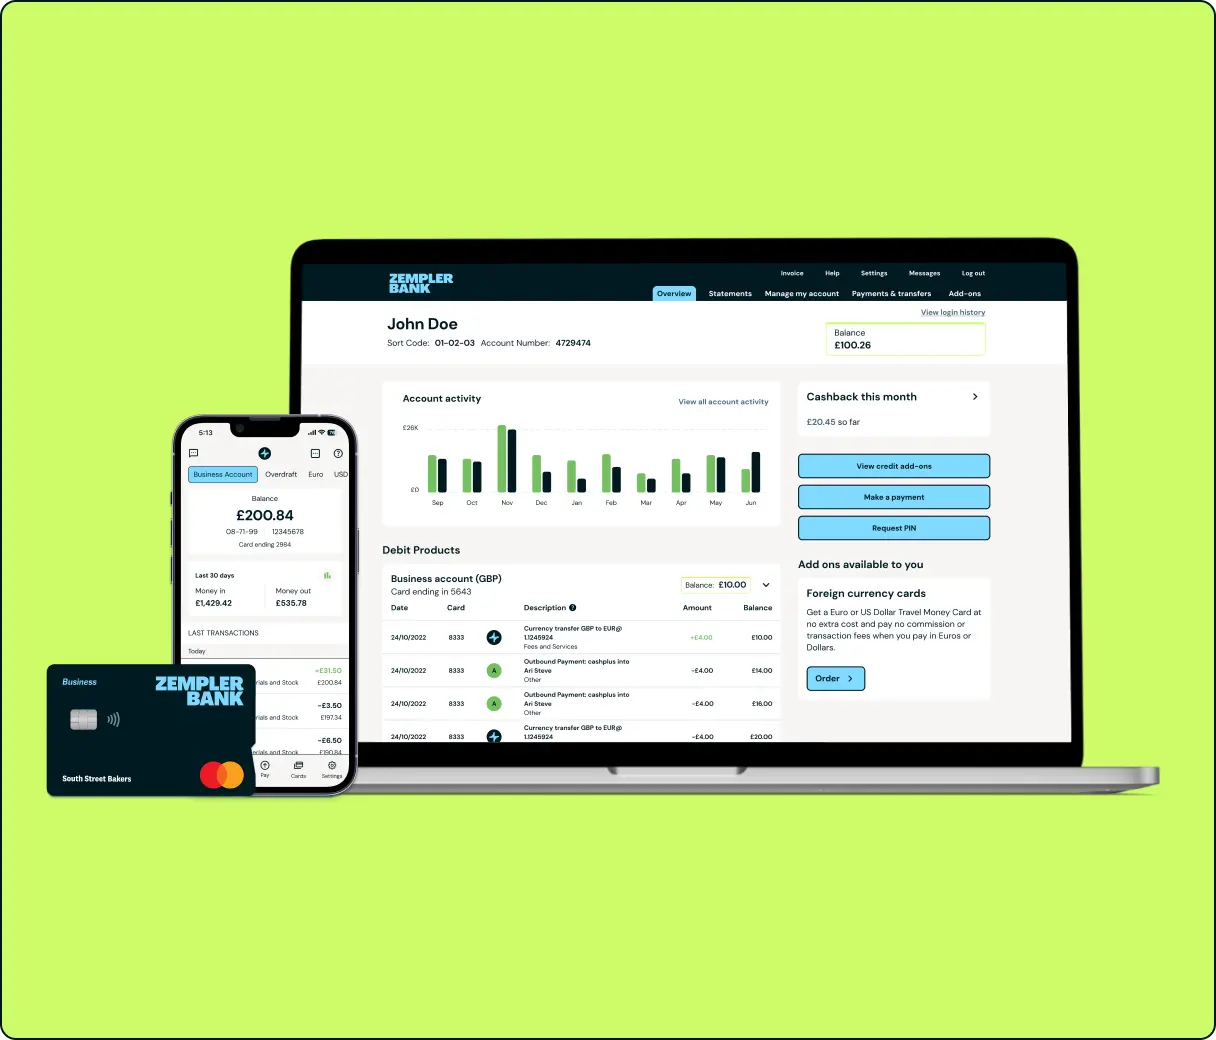
That matters because a founder’s banking app is an operating tool, not simply a place to view a balance. Clear navigation reduces friction when checking payments, moving money or locating records. Zempler also provides Online Banking, which may suit owners who prefer handling bookkeeping and admin on a larger screen.
Our testing was limited to the application, initial access and normal exploration of the account. We did not test every plan, feature, integration, support route or payment type, and we are not making claims about long-term reliability or customer service from this experience.
Business tools in this Zempler Bank review
Our Zempler Bank review found that the free tier includes more than basic payments. Zempler’s published comparison lists integrated accounting, digital invoice creation, receipt capture, cashflow tracking, set-aside pots and a Making Tax Digital integration tool across Business Go, Extra and Pro.
Invoicing and payment visibility
Zempler lets users create and send digital invoices and receive a notification when money reaches the account. For a consultant or young service business that has not purchased separate invoicing software, this can reduce the number of systems needed at launch.
It will not necessarily replace a full accounts-receivable platform for a growing company. Founders should check whether they need recurring invoices, approval workflows, payment chasing, multi-currency billing or detailed reporting before treating a bank’s built-in invoice tool as their permanent solution.
Digital receipts
Receipts can be digitised and attached to transactions in the app. This can make expense evidence easier to find and reduce the familiar year-end search through email and paper. The value is highest when the feature becomes part of a consistent process rather than an occasional upload folder.
Accounting connections
Zempler says its integrated accounting connects with software including Xero, QuickBooks and Sage. This is useful for businesses already committed to one of those systems because transaction syncing can reduce manual entry. Check the exact connection, available data and your software subscription before applying, particularly if your accountant depends on a specific workflow.
Cashflow tracking and categories
Cashflow tracking is available in the app and online, with custom categories for spending. For a new business, a simple forward view can make upcoming commitments more visible. It is an aid to management, not a replacement for a maintained cashflow forecast when payroll, tax and supplier timing become more complex.
Pots and tax discipline
Set-aside pots allow money to be allocated for taxes, costs or business goals. Separating a proportion of each receipt for VAT or self-assessment can improve discipline even though the money remains within the banking relationship. Business Pro additionally advertises a 0.75% interest-earning savings pot, subject to eligibility and balance limits.
Making Tax Digital
Zempler promotes a free Making Tax Digital tool in Online Banking for recording and submitting VAT returns. That could be valuable for an eligible small business wanting a simple route to MTD compliance. It should not be confused with comprehensive bookkeeping or tax advice, and businesses with complex VAT treatment should confirm suitability with their accountant.
Zempler Bank review of cash deposits
The cash-handling part of our Zempler Bank review highlights one of its more practical differentiators for businesses that still take notes and coins. Zempler says cash can be paid in over the counter using the account card at more than 11,500 UK Post Office branches, with funds made available immediately.
That accessibility can help tradespeople, market sellers, independent retailers and hospitality businesses that do not want a traditional branch account. The economics need attention, though. Every deposit costs at least £4, or 0.55% if that is higher.
A business depositing £200 pays the £4 minimum, equivalent to 2% of the money deposited. Combining takings into a £1,000 deposit reduces the effective rate to 0.55%, producing a £5.50 charge, but holding cash for longer can introduce security and operational risks. A cash-taking founder should model deposit frequency and average deposit size rather than simply checking that cash deposits are available.
Zempler’s published standard limit is £6,000 per day for each current business plan, with limits and review conditions applying. Cash-heavy businesses should also consider whether the Post Office process, local opening hours and deposit limits suit their routine.
Zempler does not accept cheque deposits. That is a clear limitation for any business whose customers or organisations still pay by cheque.
Is Zempler Bank safe and FSCS protected? Our Zempler Bank review answer
Zempler Bank Limited is a UK bank authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the PRA. Its Financial Services Register reference number is 671140.
Eligible deposits with Zempler Bank are protected by the Financial Services Compensation Scheme up to £120,000 per eligible depositor, per bank. The limit applies across eligible deposits held with the same authorised bank, not separately to every account. Eligibility and scheme rules matter, and FSCS deposit protection does not reimburse ordinary card-payment disputes, scams or trading losses.
The £120,000 limit took effect on 1 December 2025. Zempler’s dedicated FSCS information and pricing pages show the current amount, as does the FSCS. At the time of research, Zempler’s general legal page still contained an older £85,000 statement. We have relied on the current FSCS position and Zempler’s dedicated FSCS information, and recommend that Zempler correct the stale legal-page copy.
On account security, Zempler publishes 24/7 fraud monitoring, instant payment notifications and the ability to freeze or unfreeze the card online or in the app. These controls are useful, but no bank account removes the need for strong device security, careful payment checks and immediate reporting of suspicious activity.
Who can open an account? Zempler Bank review of eligibility
Our Zempler Bank review of eligibility found that Zempler currently accepts applications from limited companies, sole traders, charities and partnerships. Applicants must be at least 18 and UK resident, and the business must be UK based where relevant.
For a sole-trader application, the applicant must be a UK-based sole trader or freelancer and must not be registered at Companies House. For a limited company, at least one director must be UK resident, the company must be active and registered at Companies House, and its confirmation statement must be up to date. The standard structure is a company limited by shares.
Companies limited by guarantee can be considered with extra due diligence and a published £100 fee. An application for a limited company must be made by a director. Zempler asks for the date of birth and home address of major shareholders or persons with significant control.
Zempler also publishes ownership and sector restrictions. It says companies must have four or fewer PSCs, all PSCs must be over 18, overseas PSCs require additional checks, and businesses with multiple corporate PSCs are not currently accepted. A corporate shareholder can lead to an additional £100 account-opening fee if approved. Unsupported sectors include cryptocurrency traders, money-service businesses, firearms dealers, scrap-metal dealers and several other higher-risk activities.
These criteria can change and do not guarantee acceptance. Check the live eligibility page before investing time in an application.
Is Zempler Bank good for startups? Our Zempler Bank review verdict by business type
This Zempler Bank review finds that the account can work well for a startup, but the answer depends on how that startup operates.
A newly incorporated, pre-revenue company: Business Go can provide account details, a card and basic admin tools without adding a monthly subscription while the founder validates the idea. The three-payment allowance may be enough at first, but the founder should revisit the plan when supplier and software payments increase.
A freelancer or consultant: This is arguably the clearest fit. Incoming client payments are free and unlimited, while invoices, receipts, cashflow tracking and pots address common solo-business needs. A consultant paying only a few suppliers could keep core fees very low.
A tradesperson: Zempler may be attractive if customers pay by transfer and occasional cash needs to be deposited at a Post Office. Frequent cash deposits, withdrawals or numerous materials payments could make the free tier more expensive than expected.
An ecommerce founder: The account can cover day-to-day sterling banking, but overseas advertising, software, inventory and marketplace flows demand closer review. Business Go’s 2.99% non-sterling card fee and Zempler’s variable international transfer pricing could be material.
A local retailer or hospitality business: Post Office deposits are useful, but cash economics are central. Model the minimum fee, percentage fee, deposit frequency and the time needed to visit a branch. A provider with different cash handling may be cheaper despite a monthly subscription.
A growing employer: Business Pro’s payment allowance, additional cards and telephone account management may be more appropriate than Go. Even then, a company needing sophisticated permissions, bulk controls, treasury services or complex international capability should compare specialist and high-street alternatives.
When Zempler might not be the best choice
Our Zempler Bank review identifies several situations in which another provider may be a better fit:
- You send many payments every month and do not want to manage allowances or per-payment charges.
- You deposit cash frequently in small amounts, making the £4 minimum disproportionately expensive.
- You make substantial non-sterling card purchases and do not want to pay for Extra or Pro.
- You receive or send frequent international payments and need transparent, competitive multi-currency pricing before each transfer.
- Your customers pay by cheque, because Zempler does not accept cheque deposits.
- You need advanced team permissions, complex expense controls, treasury tools or banking across multiple legal entities.
- Your ownership structure or sector falls outside Zempler’s published eligibility rules.
- You require 24-hour general telephone support. Zempler’s published UK customer-service hours are Monday to Friday 8am to 6pm, Saturday 8am to 4pm and UK bank holidays 9am to 5pm, although lost or stolen card help is available 24/7.
Zempler Bank pros and cons
Pros
- Business Go has no monthly or annual account fee.
- Zempler is a regulated UK bank, with eligible deposits protected by the FSCS up to £120,000 under current scheme rules.
- Incoming payments and transfers are free and unlimited across the three current plans.
- Invoicing, receipt capture, cashflow tracking, pots and MTD tools are listed on the free plan.
- Cash can be deposited through the Post Office network.
- Our application was smooth, and we found the interface easy to navigate.
- Business Extra and Pro remove Zempler’s fees for cash withdrawals and non-sterling card spend.
Cons
- Business Go includes only three outgoing payments or transfers each month.
- Cash deposits cost at least £4 each on all three plans.
- Business Go charges 2.99% on non-sterling card transactions.
- International transfer charges are not presented as one simple public fixed price and should be checked in-app or online.
- Cheque deposits are not supported.
- Cashback is tiered, applies only to eligible purchases and excludes numerous transaction categories.
- Some ownership structures, industries and overseas PSC arrangements are not accepted or require extra checks and fees.
Zempler Bank review alternatives
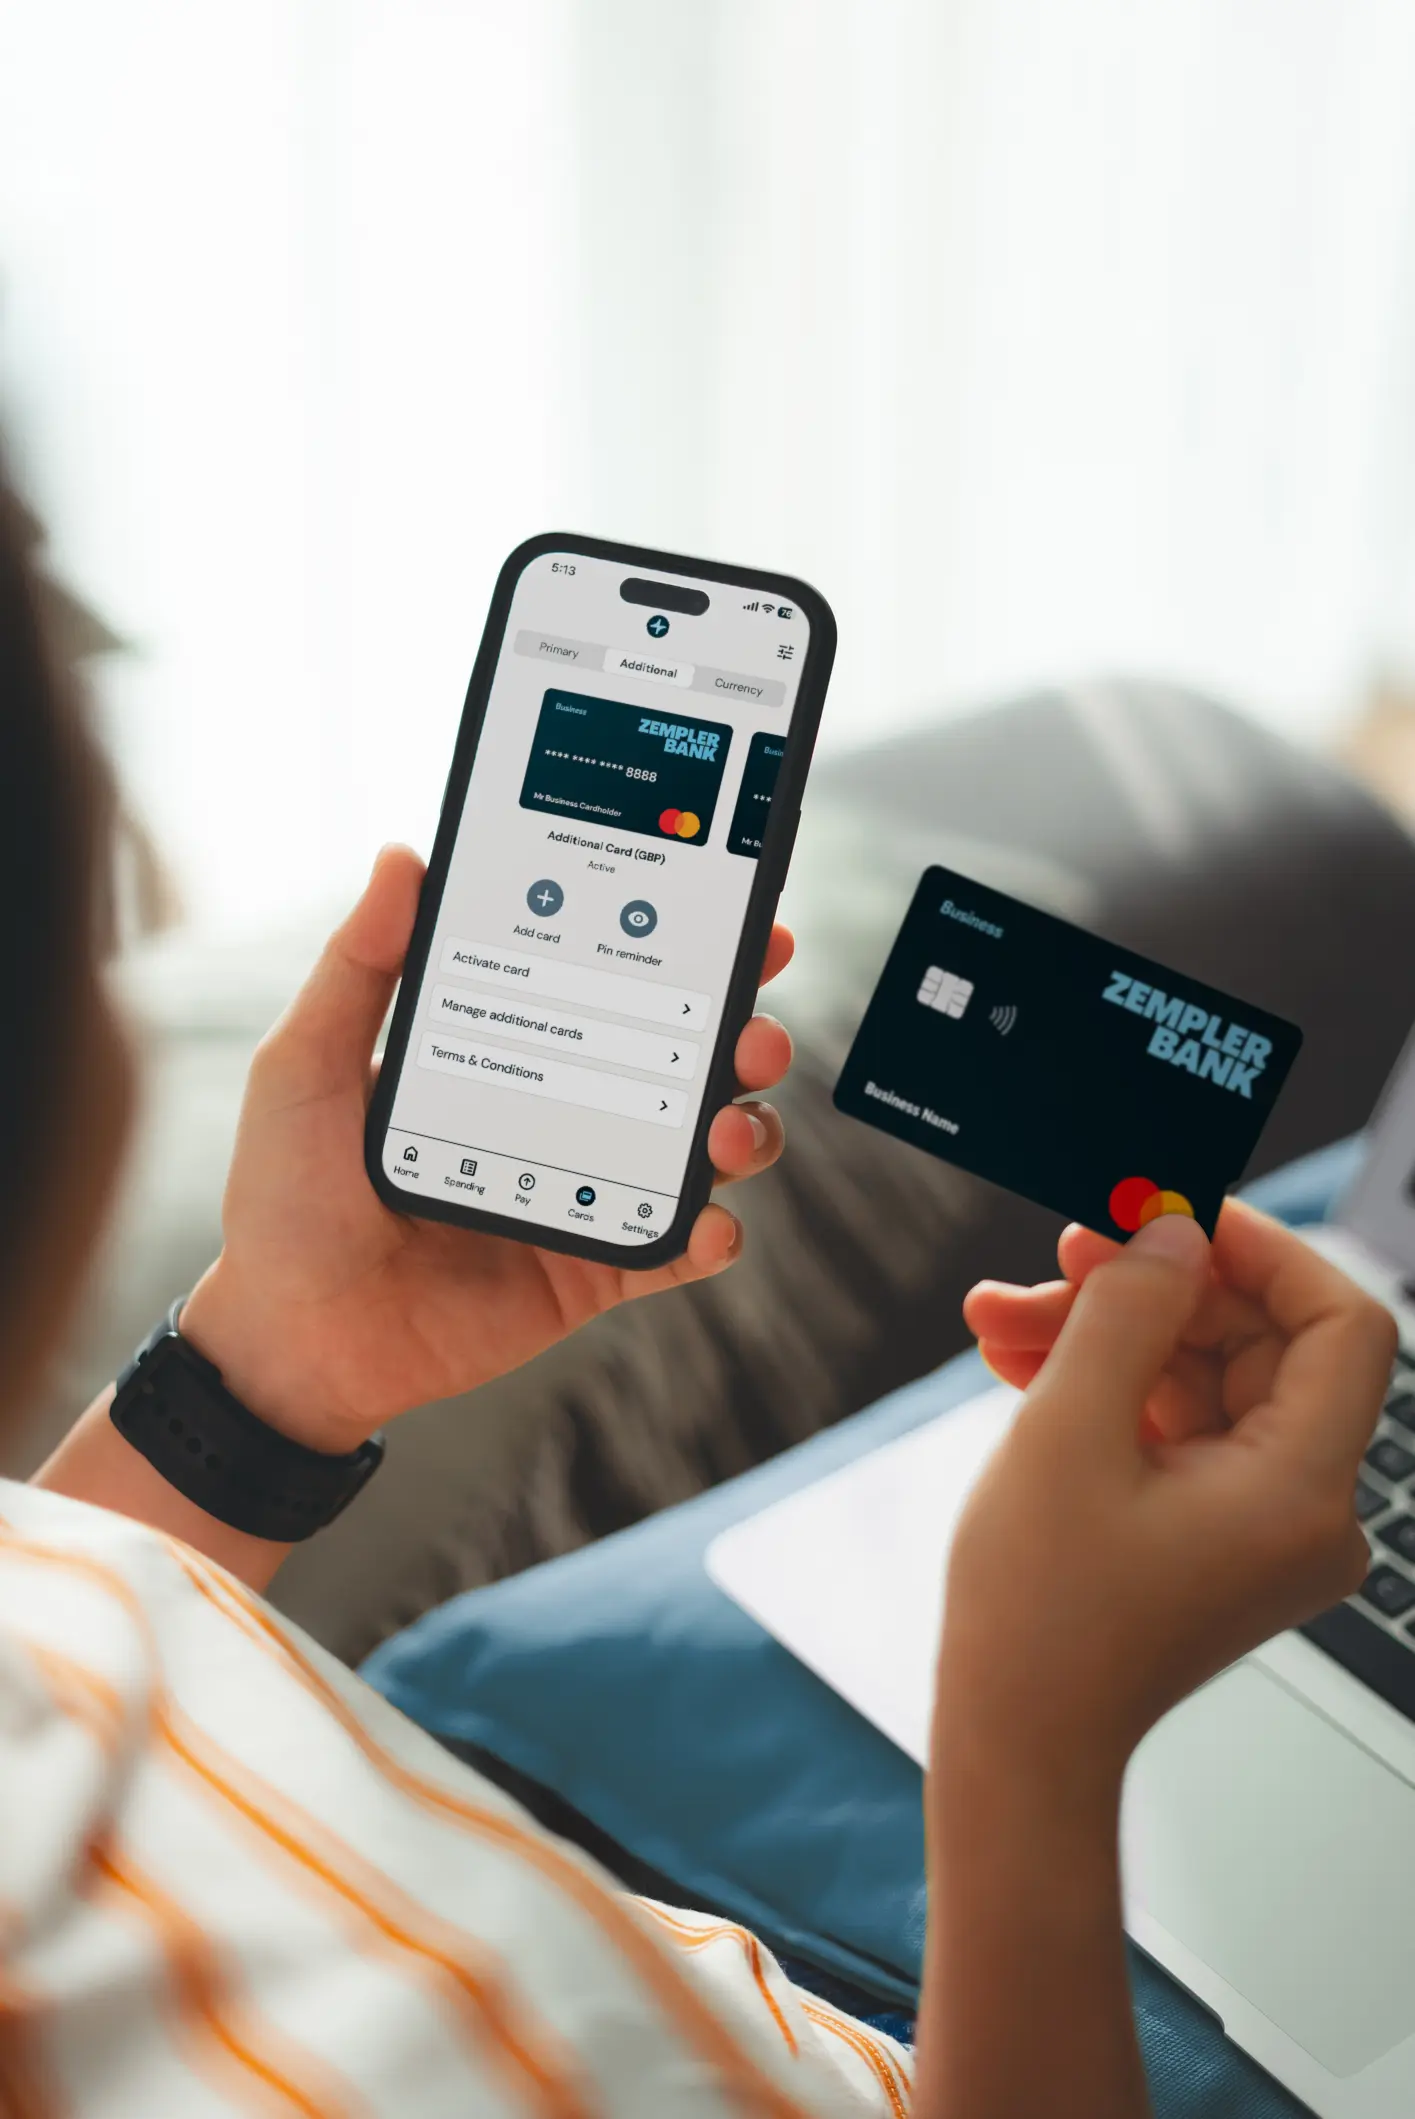
No single provider is best for every startup. The alternatives in this Zempler Bank review deserve comparison based on the operating model rather than the size of an introductory incentive. A useful Zempler review should therefore explain when another account may offer a better fit rather than presenting Zempler as a universal choice.
| Alternative | Who may prefer it | What to compare with Zempler |
|---|---|---|
| Tide | A digital-first small business focused on invoicing, expenses and a broader business platform | Transfer pricing, cash-deposit routes, FSCS status of the specific account and paid-plan value |
| Monzo Business | A founder who already likes Monzo’s interface and wants budgeting, pots and integrations in a familiar app | Monthly plan pricing, cash handling, account tools and team access |
| Mettle | A sole trader or small limited company wanting no monthly fee and close integration with FreeAgent | Eligibility, cash deposits, payment limits and whether FreeAgent fits the bookkeeping workflow |
| ANNA Money | A founder prioritising admin assistance, invoicing and tax-related organisation alongside an account | Whether the product is a bank account or e-money arrangement, usage fees and support model |
| Revolut Business | An internationally active startup needing currencies, exchange and global payment tools | Plan allowances, exchange limits, local account details, team controls and deposit protection for the specific service |
Provider features and prices change, so use this as a shortlist rather than a substitute for a current comparison. If low-cost sterling banking and Post Office deposits matter most, Zempler remains distinctive. If international activity, accounting bundling or team finance is more important, one of the alternatives may be better aligned.
How to apply for a Zempler account
Before applying, review the current plans and estimate a typical month of outgoing transfers, cash deposits, ATM use and foreign spending. Then check that your business structure, sector and ownership meet Zempler’s live eligibility criteria.
The online application asks about you and the business. Limited-company information may be obtained from Companies House, while other structures can require direct input. Zempler then carries out identity, business, KYC, fraud and eligibility checks and may request further information.
Visit Zempler Bank through Startup Deals
This is Startup Deals’ approved tracked application route. It is not a customer promo code and there is currently no exclusive Startup Deals cashback, discount or joining bonus. Check Zempler’s live pricing, terms and eligibility before applying.
Zempler Business account review FAQs
Is Zempler Bank a real bank?
Yes. Zempler Bank Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the PRA. Its FRN is 671140.
Is Zempler Bank safe?
Zempler is a regulated UK bank and publishes controls including 24/7 fraud monitoring, card freezing and payment notifications. Safety also depends on how the account holder protects devices, checks payments and responds to suspected fraud.
Is Zempler Bank FSCS protected?
Eligible deposits with Zempler Bank are covered by the Financial Services Compensation Scheme up to £120,000 per eligible depositor, per bank, subject to scheme rules. Deposits across accounts with the same authorised bank are aggregated.
Is Zempler Business Go really free?
Business Go has no monthly or annual account fee. It includes three outgoing payments or transfers per month, after which each costs 35p. Cash deposits, withdrawals, foreign card spending and some other services can also create charges.
How much does Zempler Bank cost?
Business Go costs £0 per month, Business Extra costs £9 per month and Business Pro costs £19 per month. Your total cost depends on transaction volume and chargeable activity.
Can a sole trader use Zempler?
Yes, subject to Zempler’s checks and eligibility criteria. Zempler says the applicant must be a UK-based sole trader or freelancer and not registered at Companies House.
Can a limited company use Zempler?
Yes, if it meets Zempler’s eligibility and verification requirements. At least one director must be UK resident, the business must be UK based and active at Companies House, and the application must be made by a director.
Can I pay cash into Zempler Bank?
Yes. Business customers can deposit cash at UK Post Office branches using their account card. The published fee is a £4 minimum or 0.55% of the amount deposited, with limits applying.
Does Zempler Bank accept cheques?
No. Zempler’s pricing and help pages state that cheque deposits are not accepted.
Does Zempler work with Xero and QuickBooks?
Zempler says its integrated accounting connects with Xero, QuickBooks and Sage. Confirm the exact functionality and compatibility required by your bookkeeping process before applying.
How long does Zempler take to open?
There is no single guaranteed time for every applicant. Our account was opened within 24 hours after a few manual checks. Approval speed will depend on verification, business structure and any information Zempler requires.
Is Zempler good for startups?
It can be. Business Go is particularly attractive for a UK startup with few outgoing payments and limited cash or international activity. This Zempler review finds that a busier business should model the fees or consider Extra, Pro and competing accounts.
What are the disadvantages of Zempler Bank?
The main disadvantages are Business Go’s small outgoing-payment allowance, cash-deposit fees, foreign-transaction charges on Go, no cheque deposits and restrictions for certain sectors or complex ownership structures.
Does Startup Deals have a Zempler promo code?
No. Startup Deals currently has an approved tracked Zempler application link, but no exclusive customer cashback, discount, joining bonus or promo code. BAS460 is part of the tracking URL and should not be entered or promoted as a customer code.
Sources and methodology
This Zempler Bank review combines three types of evidence:
- First-hand experience: Startup Deals completed the application, went through manual checks, accessed the approved account and assessed the initial interface and feature organisation. We did not test every plan, feature, payment type, support channel, integration or long-term service outcome.
- Provider-published information: Plans, prices, allowances, cash facilities, product tools, eligibility and support details were checked against Zempler’s official pricing, product, help, eligibility, limits, contact and legal pages on 13 September 2026.
- Regulatory sources: Bank authorisation was checked against the FCA Financial Services Register. The current £120,000 deposit-protection limit was checked with the FSCS and Zempler’s dedicated FSCS information.
Fees, features, eligibility rules and promotions can change. Recheck Zempler’s pricing, cashback rules, eligibility page, terms and FSCS information immediately before publication and periodically after publication.
Final verdict: should a startup choose a Zempler business account?
The decisive finding from our Zempler Bank review is that Business Go can be a genuinely low-cost operating account, but only for the right transaction pattern. The central conclusion of this Zempler review is that a founder receiving bank transfers, making a handful of payments and working mainly in sterling gets a regulated account, current FSCS protection and a useful collection of admin tools without a subscription.
Zempler becomes less attractive when the business sends many transfers, regularly deposits small amounts of cash or spends internationally on the free tier. In those cases, Business Extra, Business Pro or a competitor should be compared using a realistic month of activity.
We would consider Zempler for a new UK business with simple banking needs. Our own onboarding experience was smooth and the interface made a strong first impression. That supports the account’s usability case, but our recommendation ultimately rests on the published fees and fit. Calculate your likely usage first, check eligibility and choose the plan that costs least for the way your business actually runs.
For more information about Zempler or other business bank account alternatives, take a look at our comprehensive reviews via our sister website TheBusinessKit.
Latest Posts:
- Zempler Bank Review 2026: Is It Good Value for UK Startups?
 Introduction Zempler Bank offers a genuine UK business bank account from £0 per month, with app and online banking, Post Office cash deposits and built-in tools for invoicing, receipts and… Read more: Zempler Bank Review 2026: Is It Good Value for UK Startups?
- Hoxton Mix vs Virtually There: Which Virtual Office Service Is Better?
 Introduction If you’re comparing Hoxton Mix vs Virtually There, you’re likely searching for a virtual office provider that offers the right balance of professionalism, affordability, and flexibility. Whether you’re launching… Read more: Hoxton Mix vs Virtually There: Which Virtual Office Service Is Better?
- Hoxton Mix vs Icon Offices: Which Virtual Office Is Better?
 Introduction Choosing a virtual office provider can have a significant impact on how your business is perceived, how you manage your mail, and even how effectively you maintain privacy as… Read more: Hoxton Mix vs Icon Offices: Which Virtual Office Is Better?
- 7 Powerful Benefits of Using a Hoxton Mix Virtual Office Address
 Introduction For startups, freelancers, sole traders and growing SMEs, establishing a professional business presence can be challenging. Renting physical office space in London is often expensive, particularly during the early… Read more: 7 Powerful Benefits of Using a Hoxton Mix Virtual Office Address
- Hoxton Mix Review: Features, Pricing, Pros and Cons Explained
 Introduction If you’re searching for an honest and detailed hoxton mix review, you’re likely comparing virtual office providers and trying to decide whether Hoxton Mix offers good value for your… Read more: Hoxton Mix Review: Features, Pricing, Pros and Cons Explained
- Hoxton Mix Virtual Office Discount: Save 10% on Your First 12 Months
 Introduction If you’re looking for a professional London business address without the cost of renting physical office space, a Hoxton Mix Virtual Office discount could help you reduce your startup… Read more: Hoxton Mix Virtual Office Discount: Save 10% on Your First 12 Months
- Tide Referral Code 2026: Powerful Guide to Claim £200 Cashback with STARTUP200
 Introduction If you’re looking for a Tide referral code in 2026, you’re probably searching for the best possible deal before opening a business account. Whether you’re a sole trader, freelancer,… Read more: Tide Referral Code 2026: Powerful Guide to Claim £200 Cashback with STARTUP200
- Tide vs High Street Banks: Powerful 2026 Review
 Introduction Choosing the right business banking solution is one of the most important decisions a UK business owner can make. Whether you’re a sole trader, freelancer, contractor, startup founder, or… Read more: Tide vs High Street Banks: Powerful 2026 Review
- Tide Business Account for Tradespeople | Powerful Guide 2026
 Introduction Running a trade business involves much more than completing jobs and keeping customers happy. Whether you’re a plumber, electrician, builder, carpenter, roofer, landscaper, painter, heating engineer, or general contractor,… Read more: Tide Business Account for Tradespeople | Powerful Guide 2026